Insights
Plain-language notes on income tax, GST, TDS, payroll, subsidies, loans and FEMA for businesses in Vadodara and across Gujarat — what changed, and what to do about it.
 GST
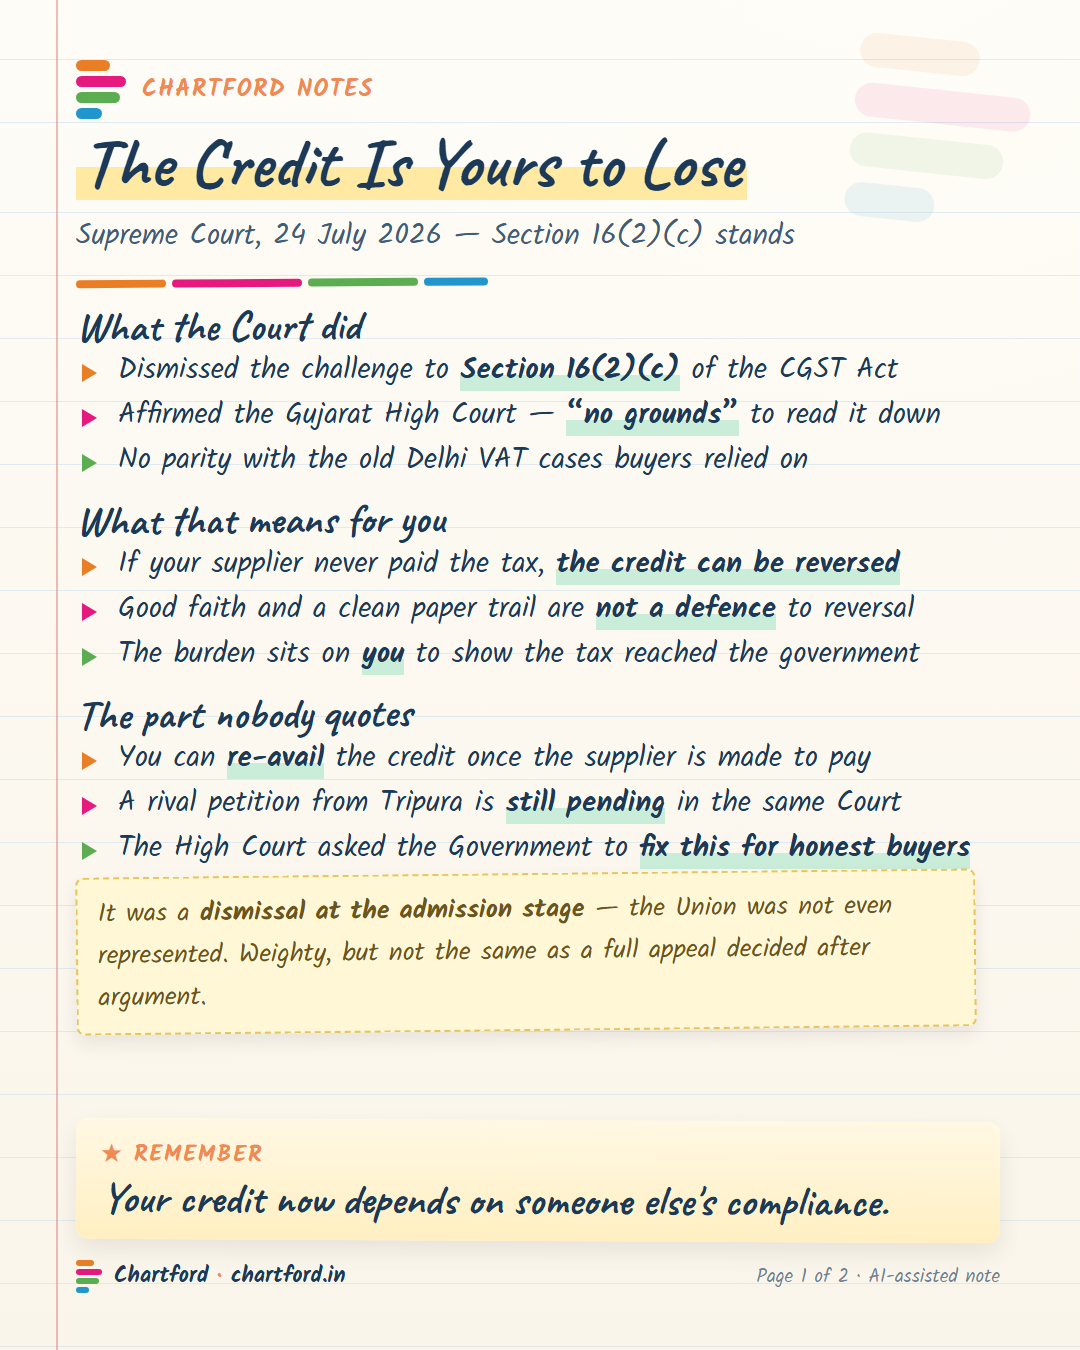
Supplier Didn't Pay GST? Your ITC Is at Risk
SC (24 Jul 2026) upheld Section 16(2)(c): if your supplier never paid the tax, your credit can be reversed. What the order says, and what to do.
Read the note →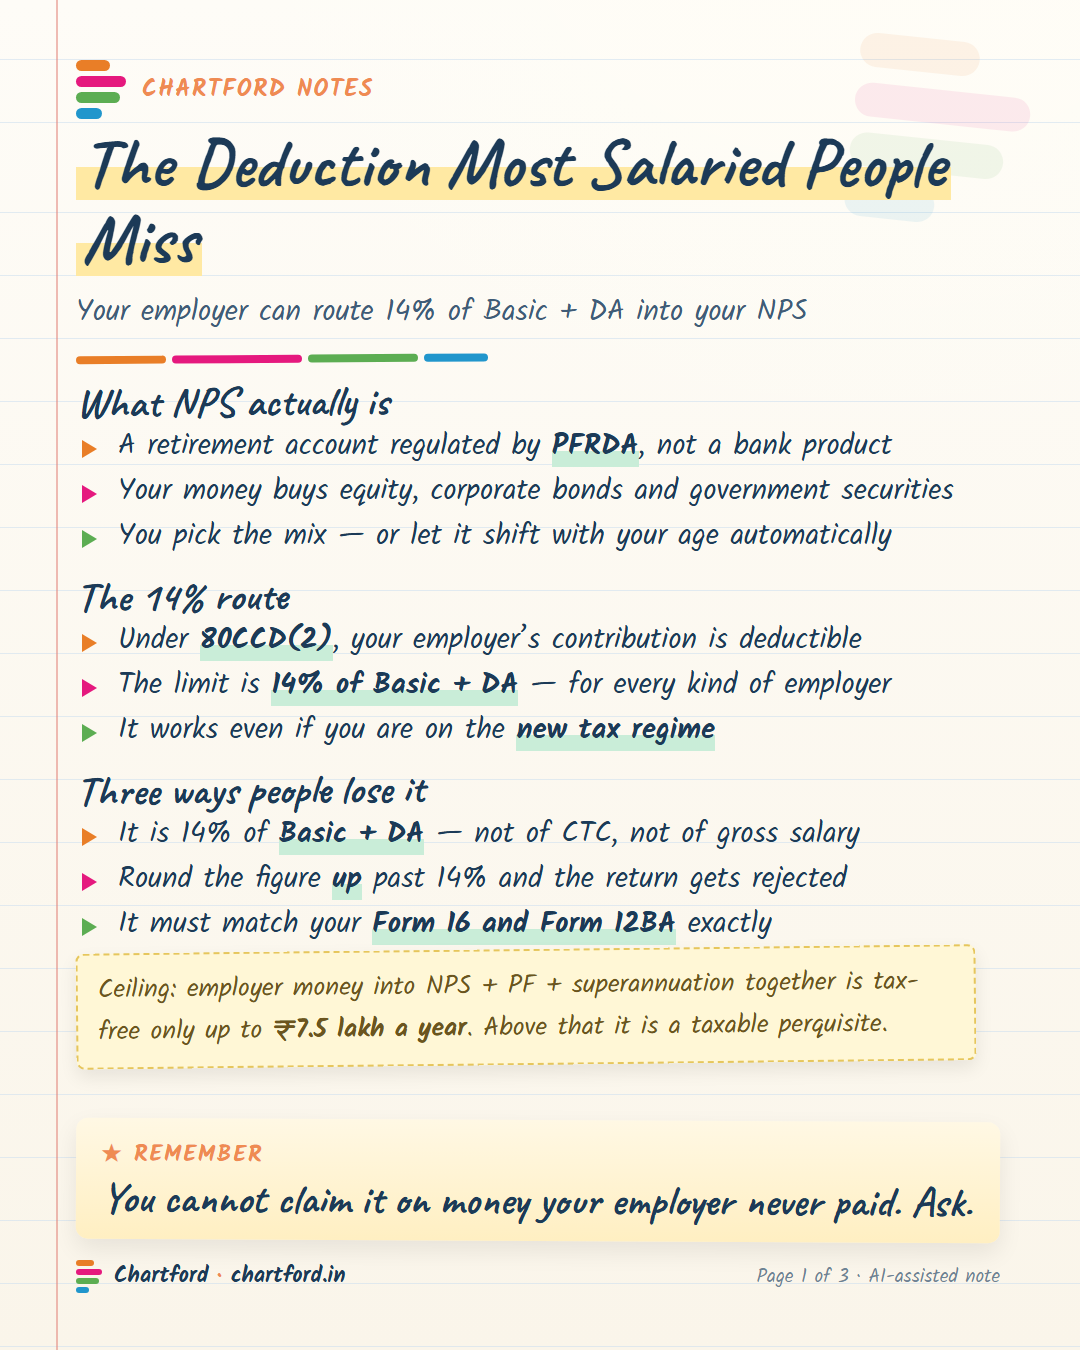 Income Tax
NPS for Salaried People: the 14% You Can Claim
Your employer can route 14% of Basic + DA into NPS under 80CCD(2). What it returns against mutual funds, when you can withdraw, and what your family gets.
Read the note →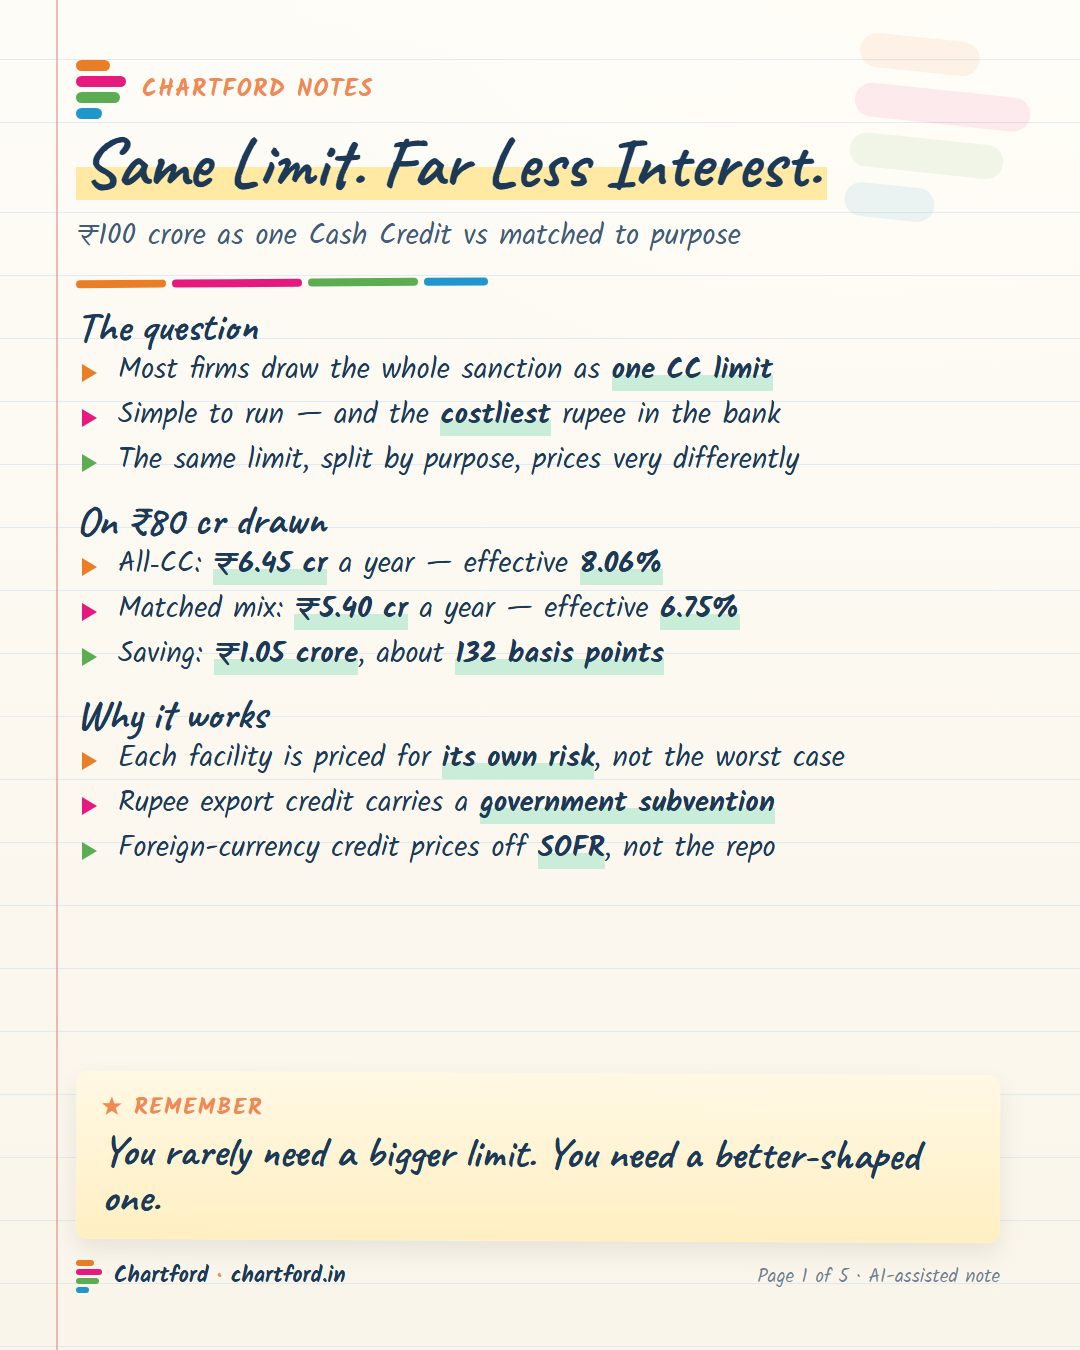 Subsidy & Loans
Same limit, same bank, ₹1.05 crore less interest: how the shape of your working capital decides what it costs
Same Rs 100 cr limit, same bank: one Cash Credit costs Rs 6.45 cr a year, a purpose-matched mix Rs 5.40 cr. Includes a calculator to run your own numbers.
Read the note →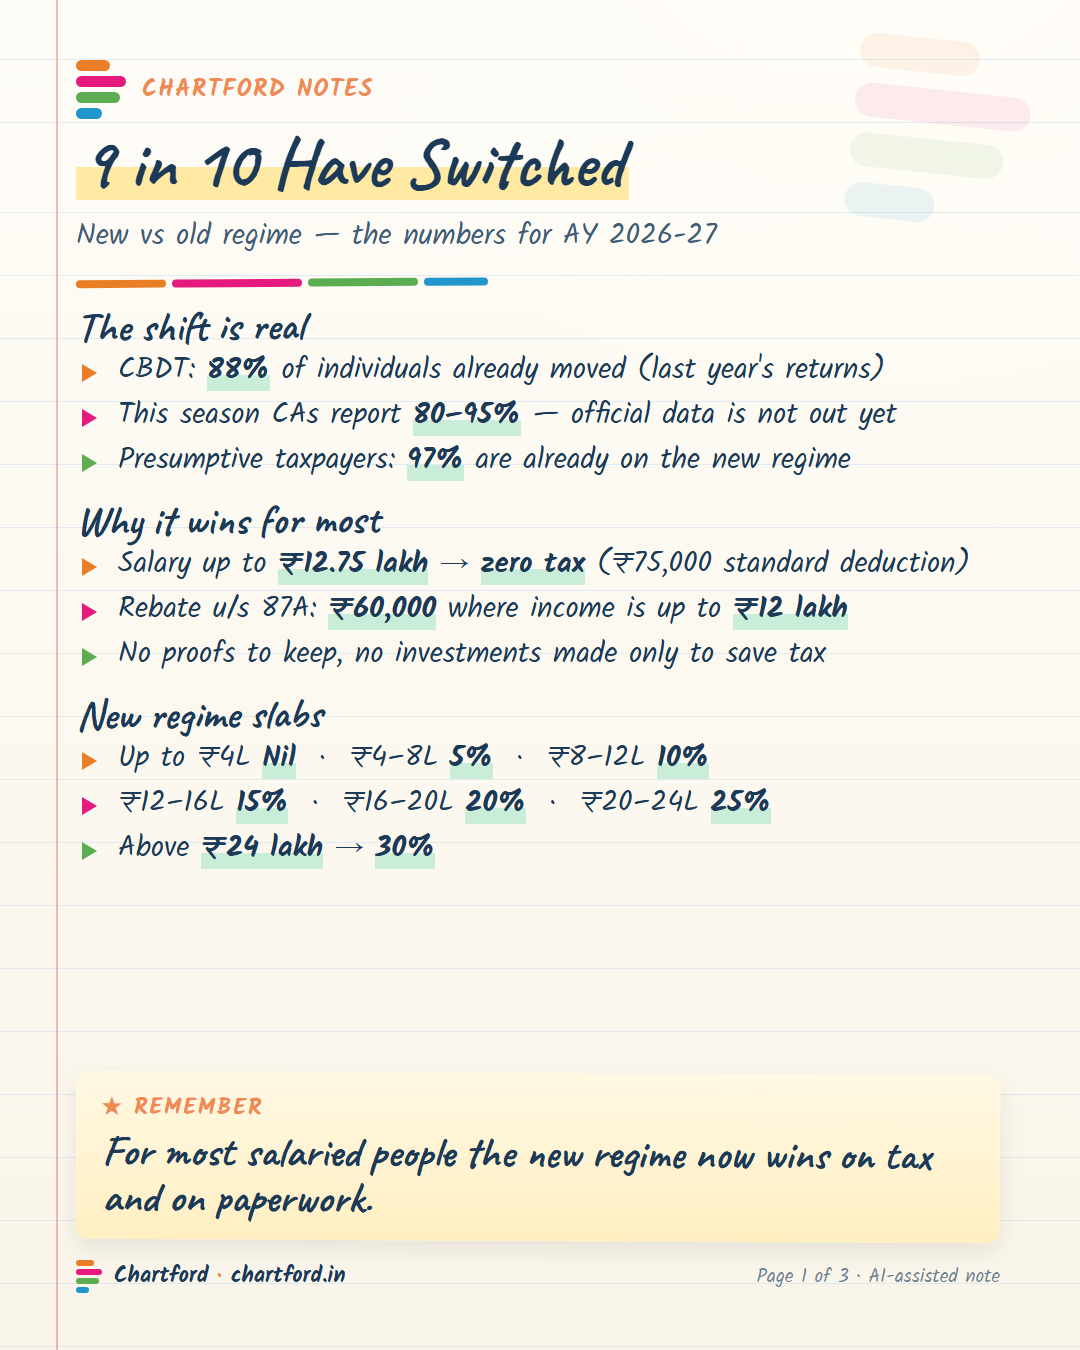 Income Tax
Nine in ten have moved to the new tax regime. Should you?
Nine in ten taxpayers have moved to the new regime. Slabs, the Rs 60,000 rebate, Rs 12.75 lakh nil-tax salary - and when the old regime still costs you less.
Read the note →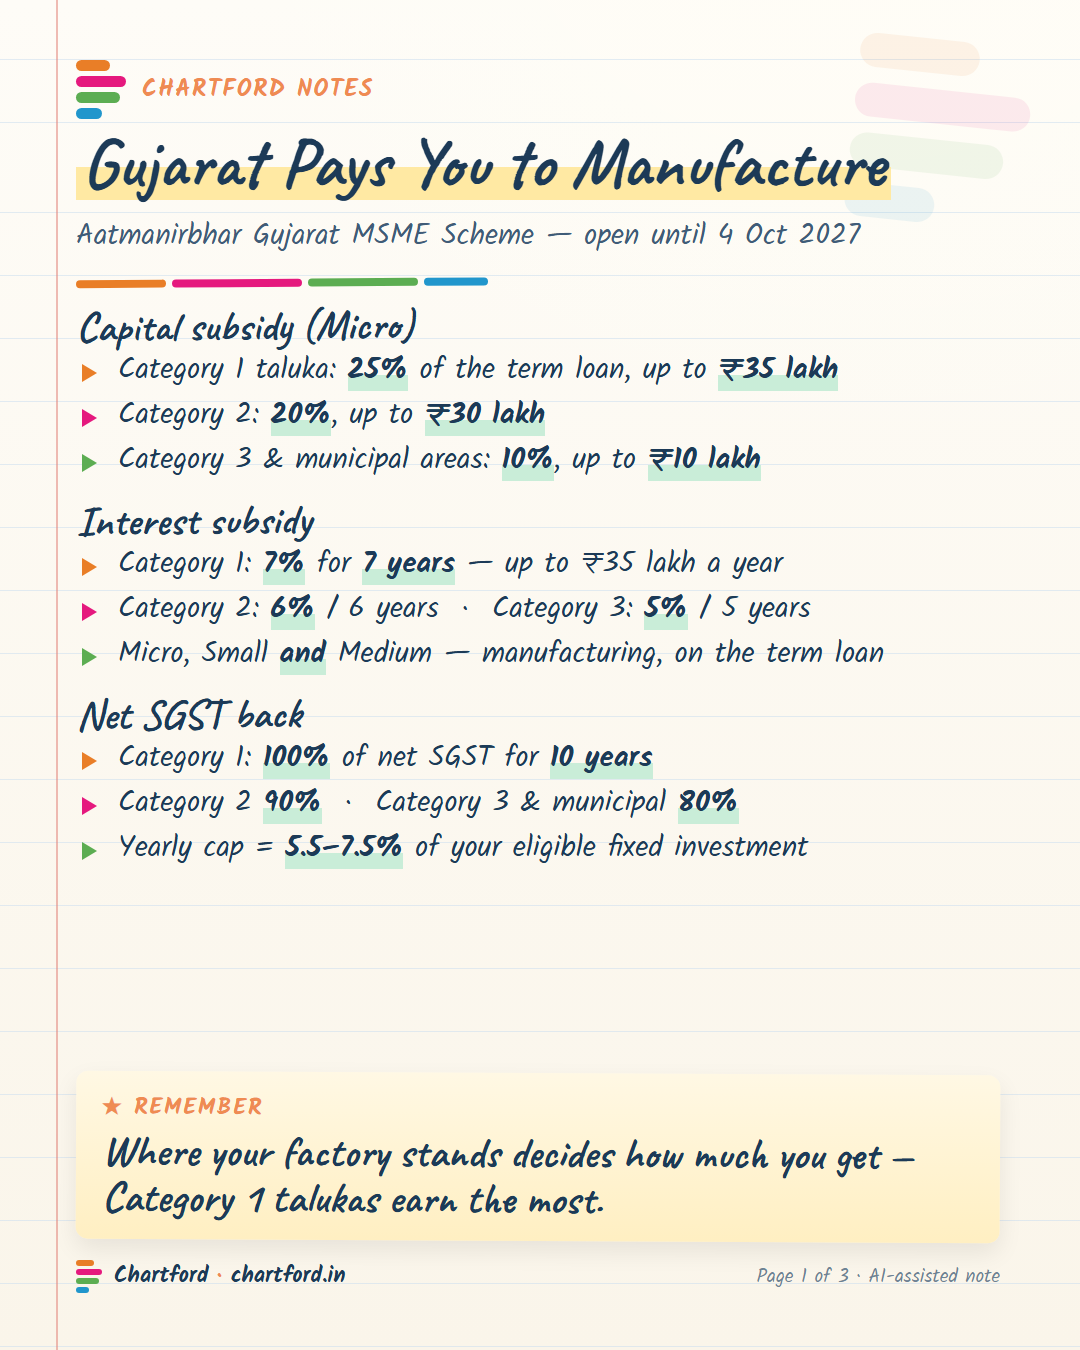 Subsidy & Loans
Gujarat MSME subsidies: every scheme a manufacturer can claim, in one place
Every Gujarat MSME subsidy in one place: capital subsidy up to Rs 35 lakh, 7% interest subsidy, 100% net SGST back, plus patent, rent and technology grants.
Read the note →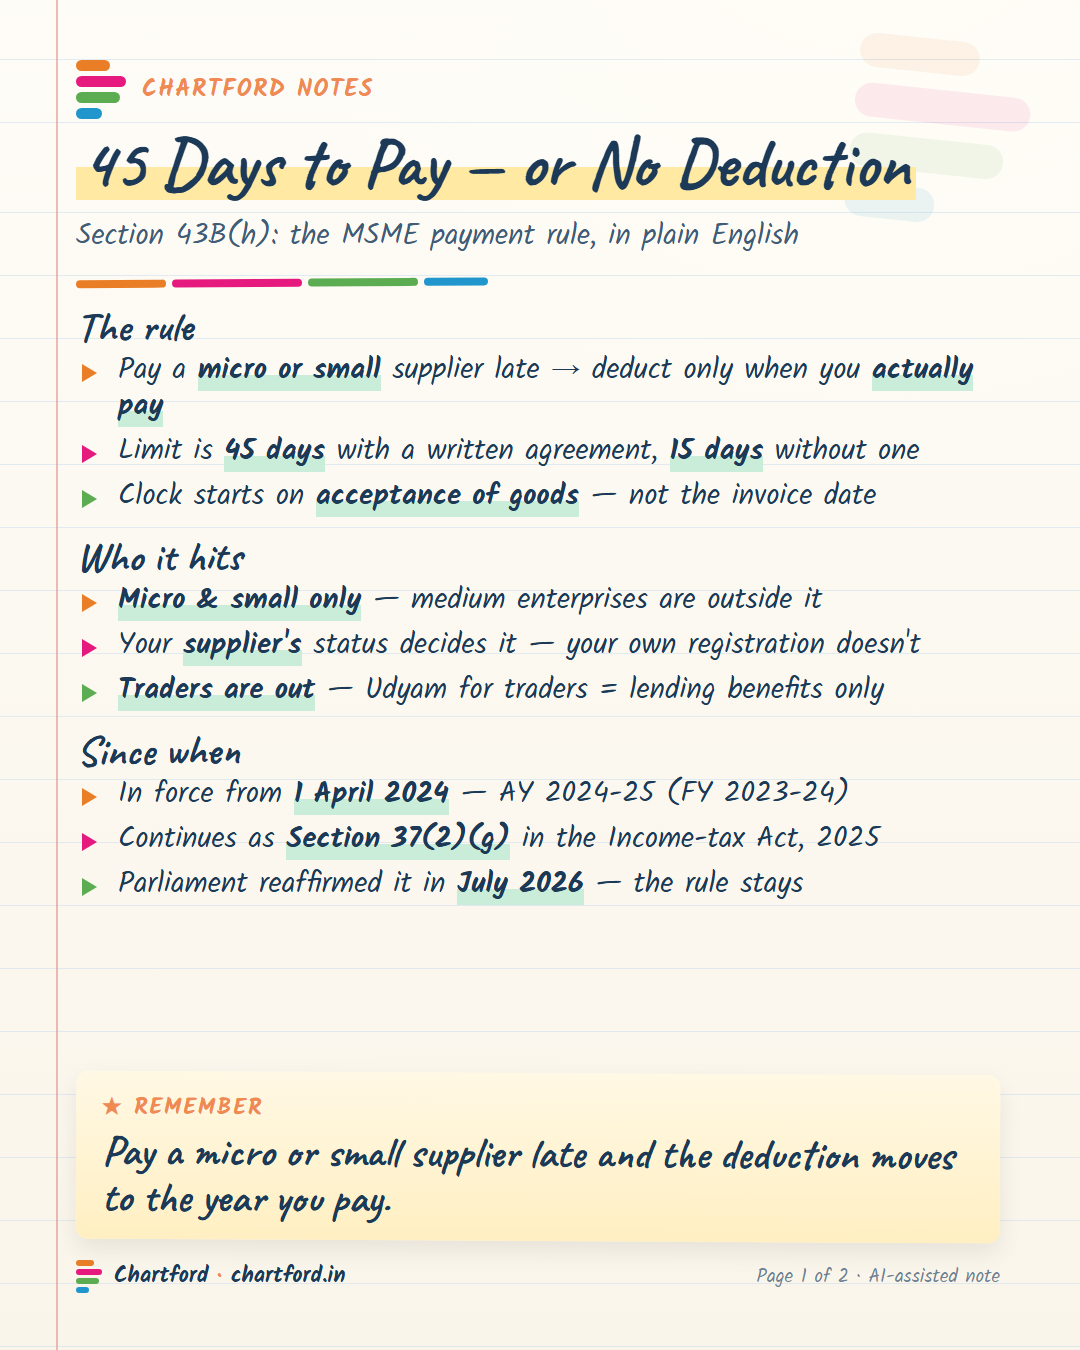 MSME
Pay your micro and small suppliers in 45 days — or your deduction waits a year
Section 43B(h): pay a micro or small supplier late and your deduction moves to the year you actually pay — and paying before the ITR due date will not save it.
Read the note →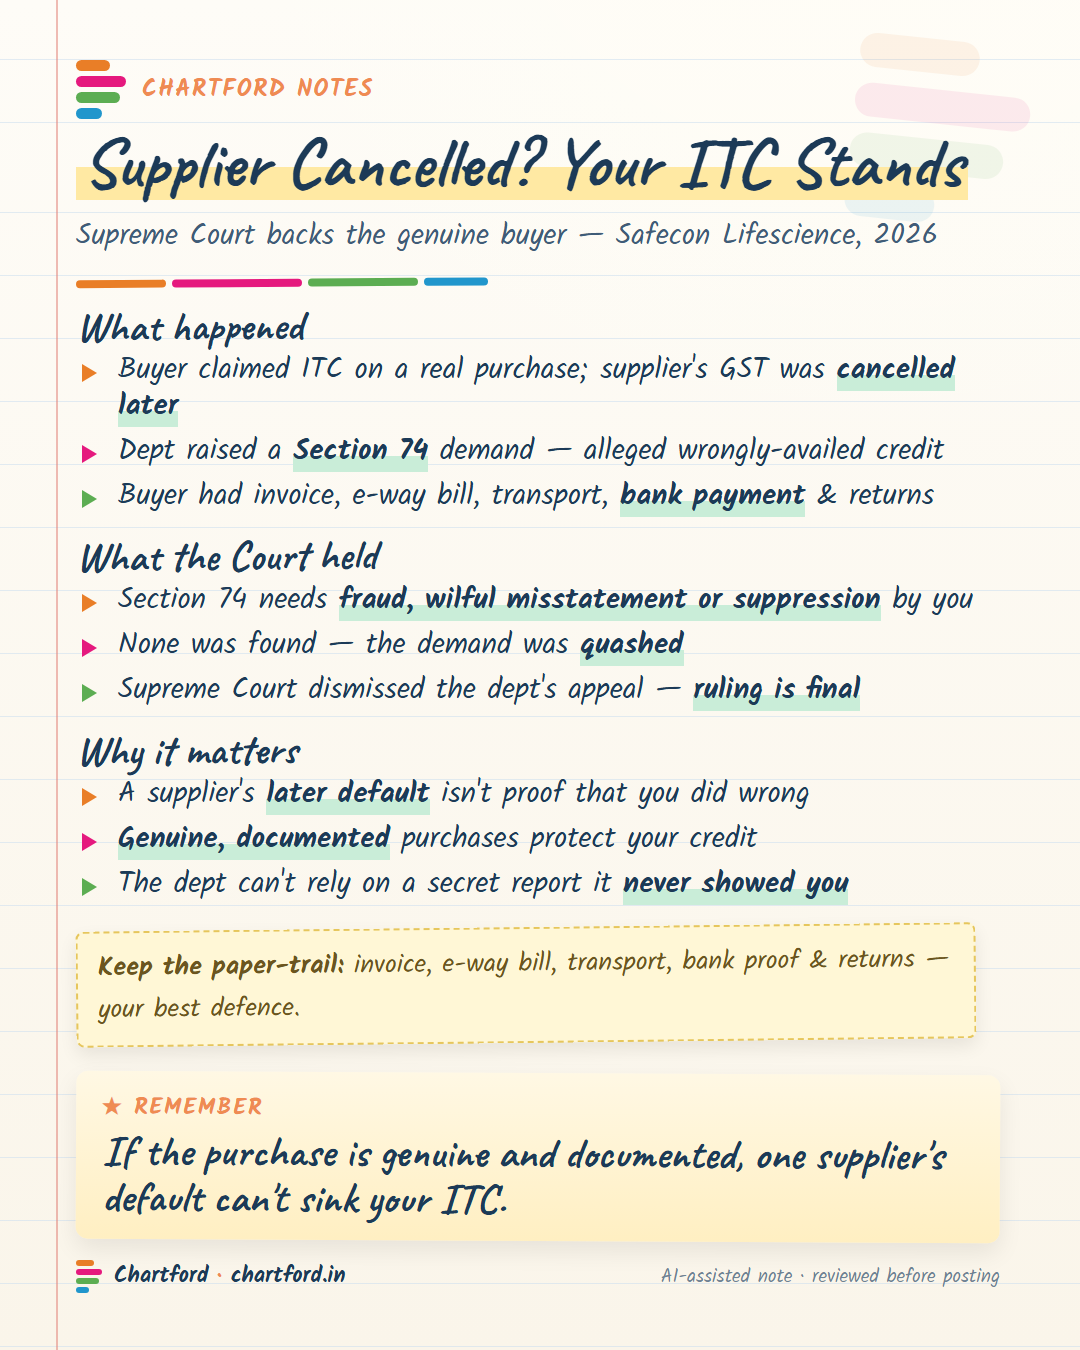 GST
Supplier's GST cancelled later? The Supreme Court just protected the genuine buyer's ITC
SC (Safecon Lifescience, 2026): a genuine, documented buyer can't lose GST input tax credit under Section 74 just because the supplier was later deregistered.
Read the note →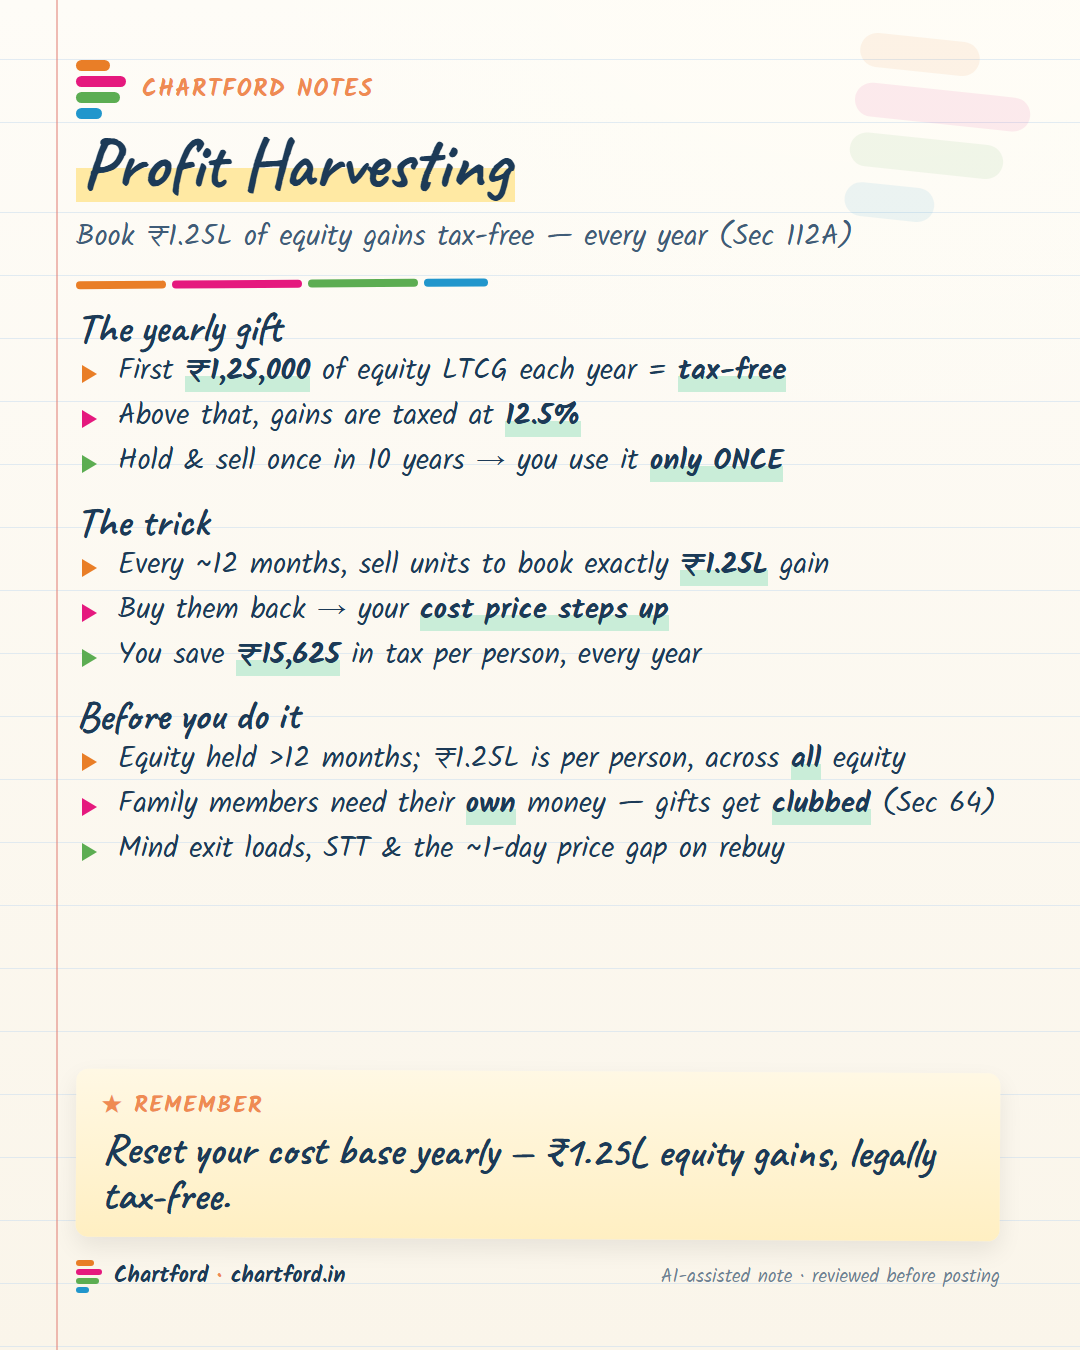 Income Tax
Profit harvesting: how to book ₹1.25 lakh of equity gains tax-free every year
Profit harvesting: book ₹1.25 lakh of equity LTCG tax-free every year (Section 112A), reset your cost base, and save ₹15,625 in tax per person annually. How it works.
Read the note →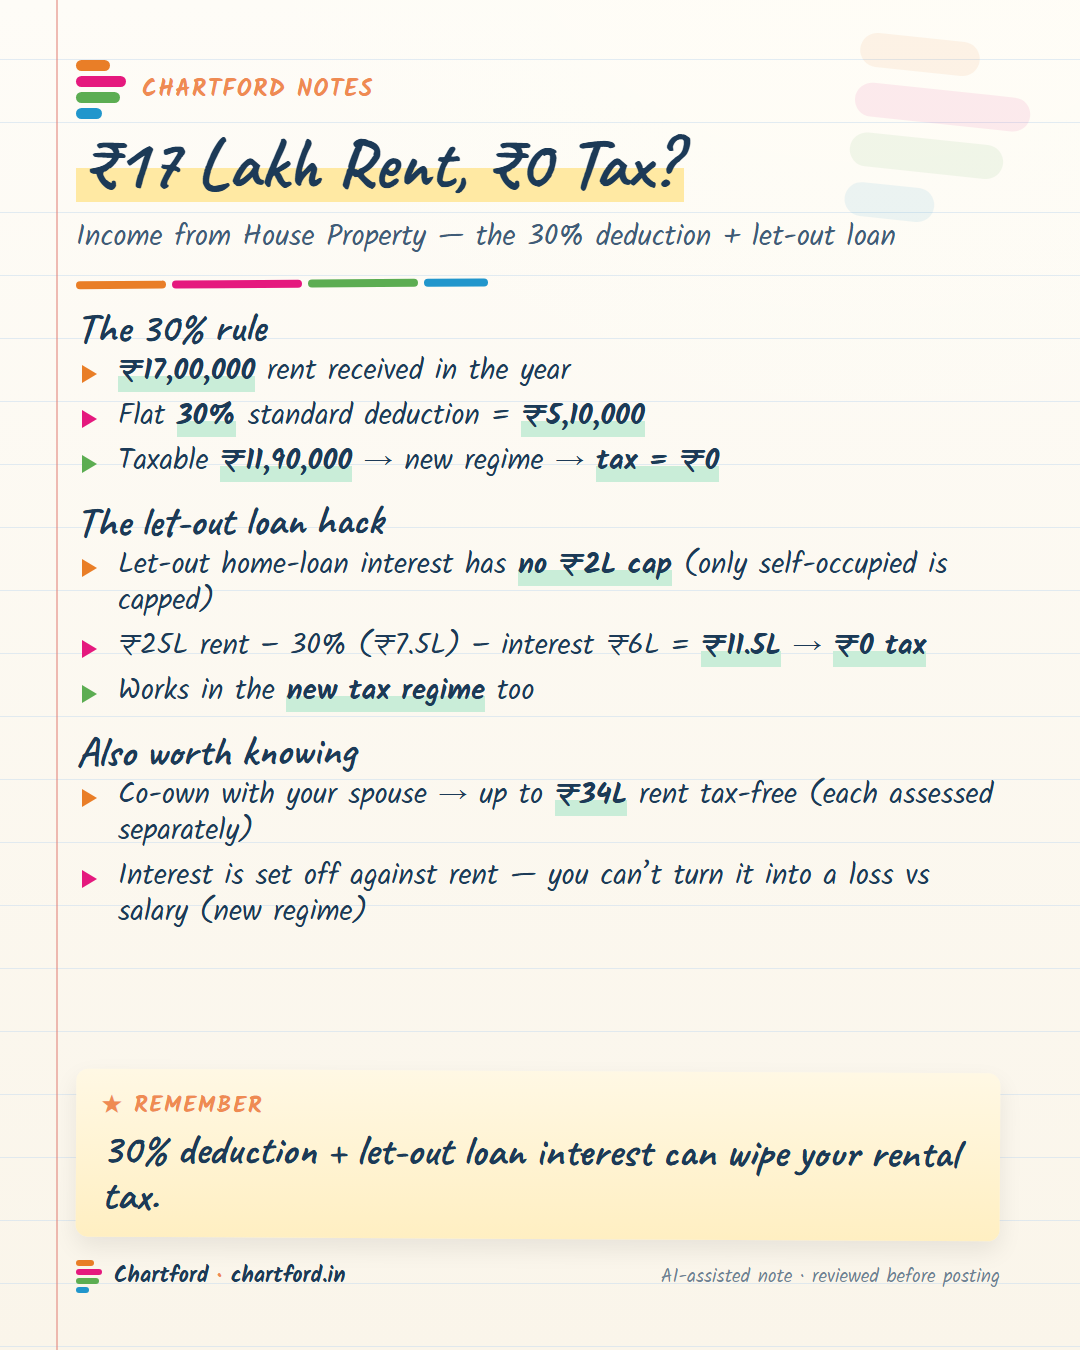 Income Tax
₹17 lakh in rent, zero tax? The house-property strategy for landlords
Landlords: earn up to ₹17 lakh rent with zero income tax via the flat 30% standard deduction — and uncapped home-loan interest on let-out property. How it works.
Read the note →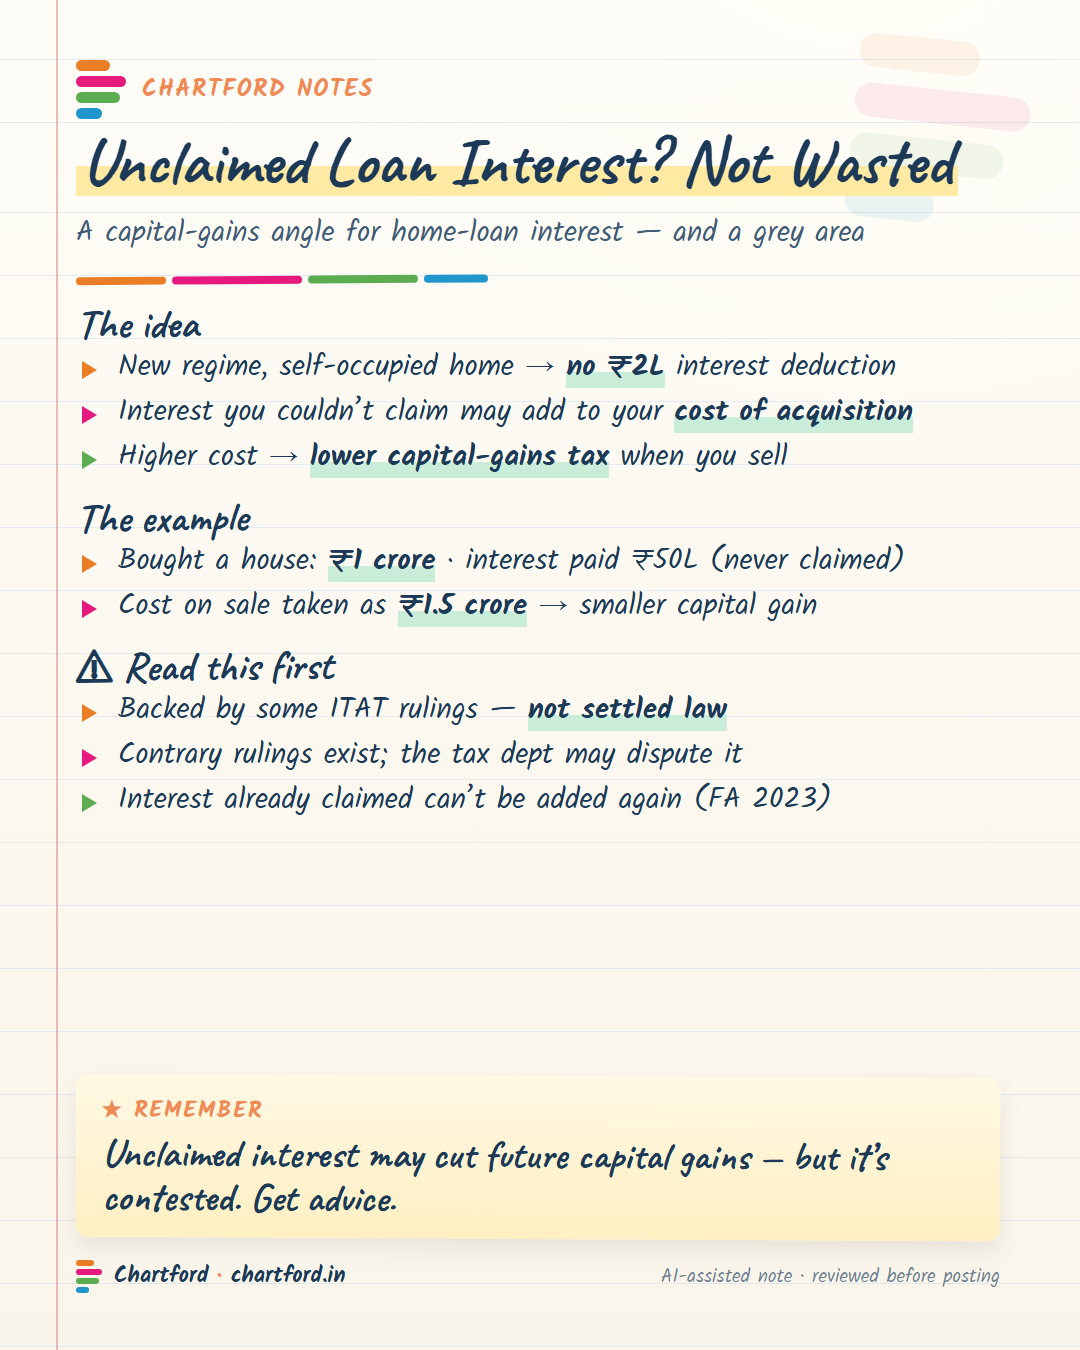 Income Tax
Unclaimed home-loan interest? It may cut your capital-gains tax later
Couldn't claim your home-loan interest under the new regime? Some ITAT rulings allow adding it to your cost of acquisition to cut capital gains — a contested position.
Read the note →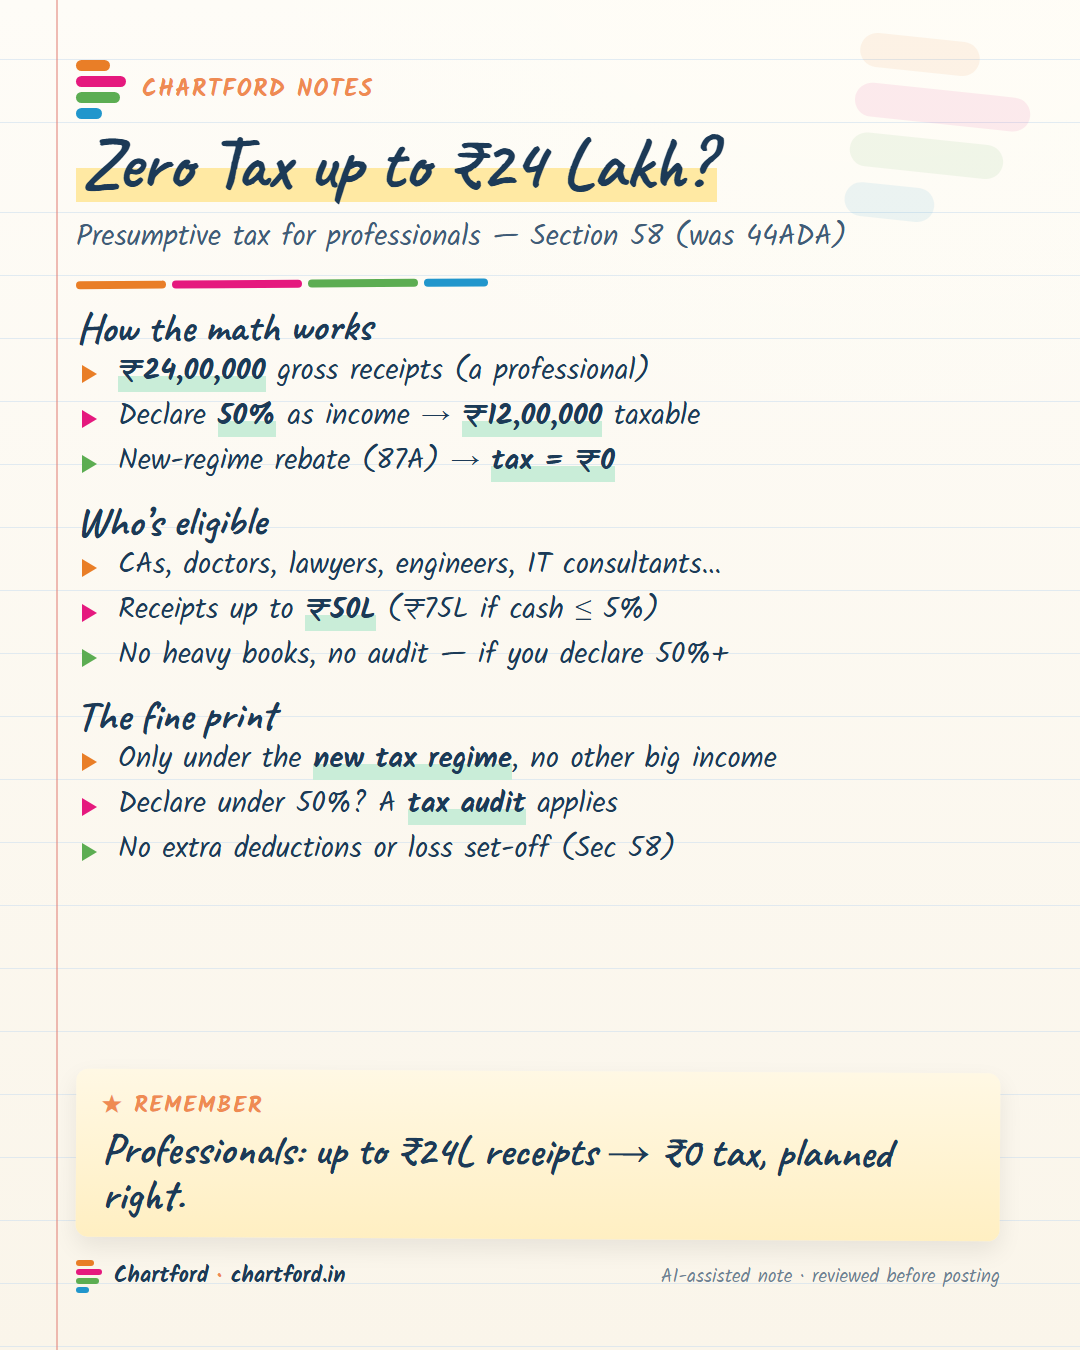 Income Tax
Zero tax up to ₹24 lakh? The presumptive-tax rule for professionals
Professionals: zero tax on up to ₹24 lakh of receipts — 50% presumptive income under Section 58 plus the new-regime rebate. How it works, who qualifies, conditions.
Read the note →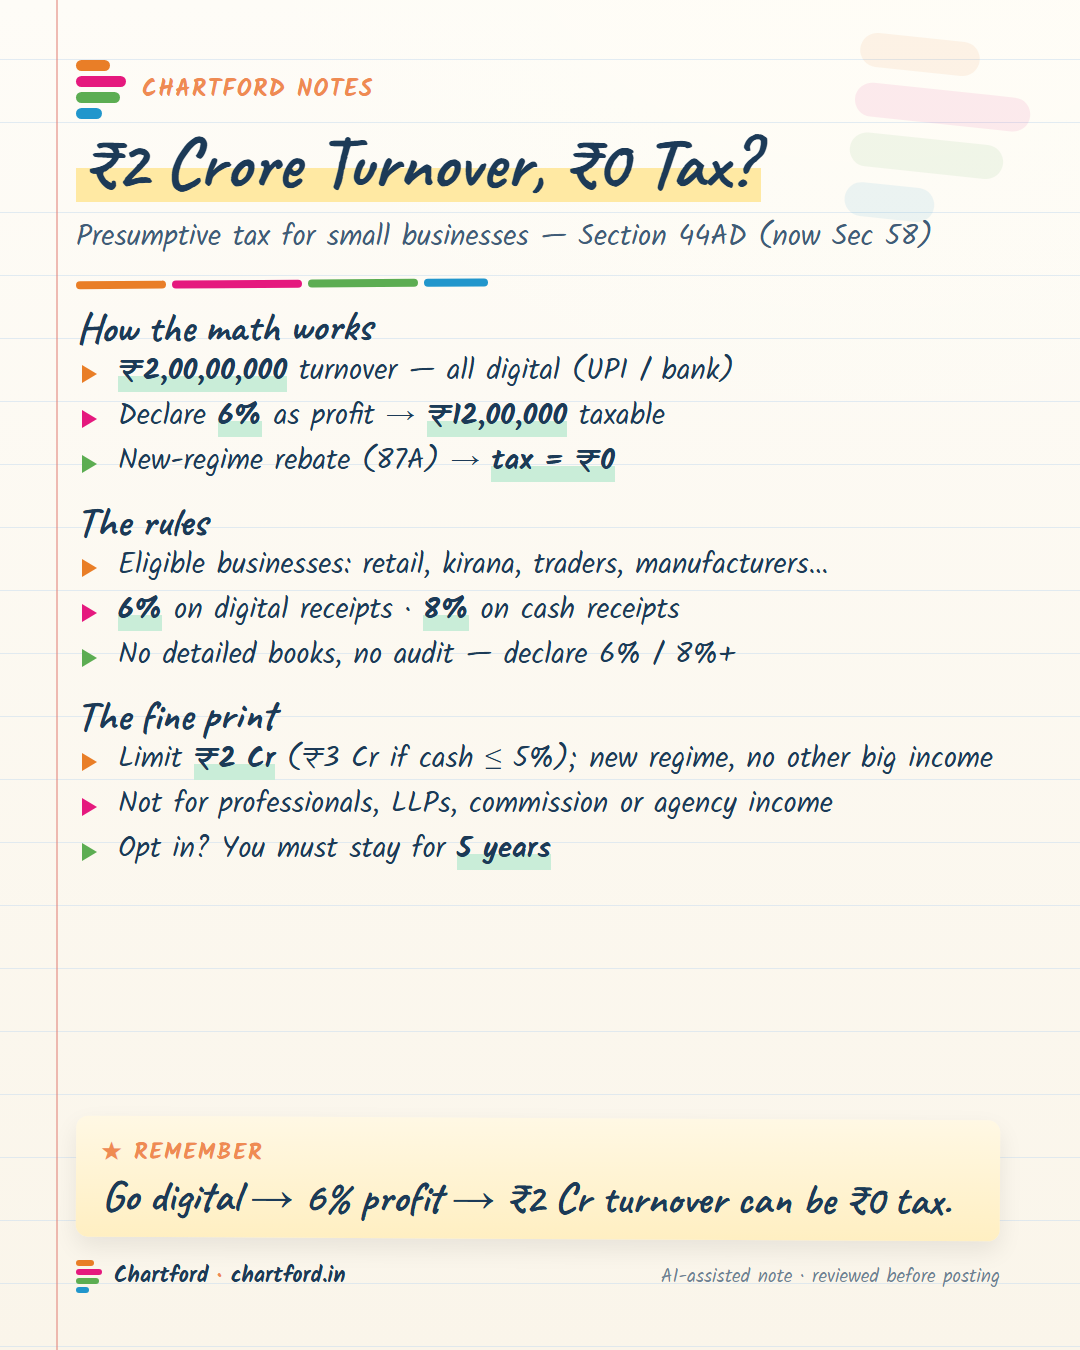 Income Tax
₹2 crore turnover, zero tax? The presumptive scheme for small businesses
Small businesses: up to ₹2 crore turnover with zero income tax — 6% presumptive profit on digital receipts (Section 44AD) and the new-regime rebate. How and who qualifies.
Read the note →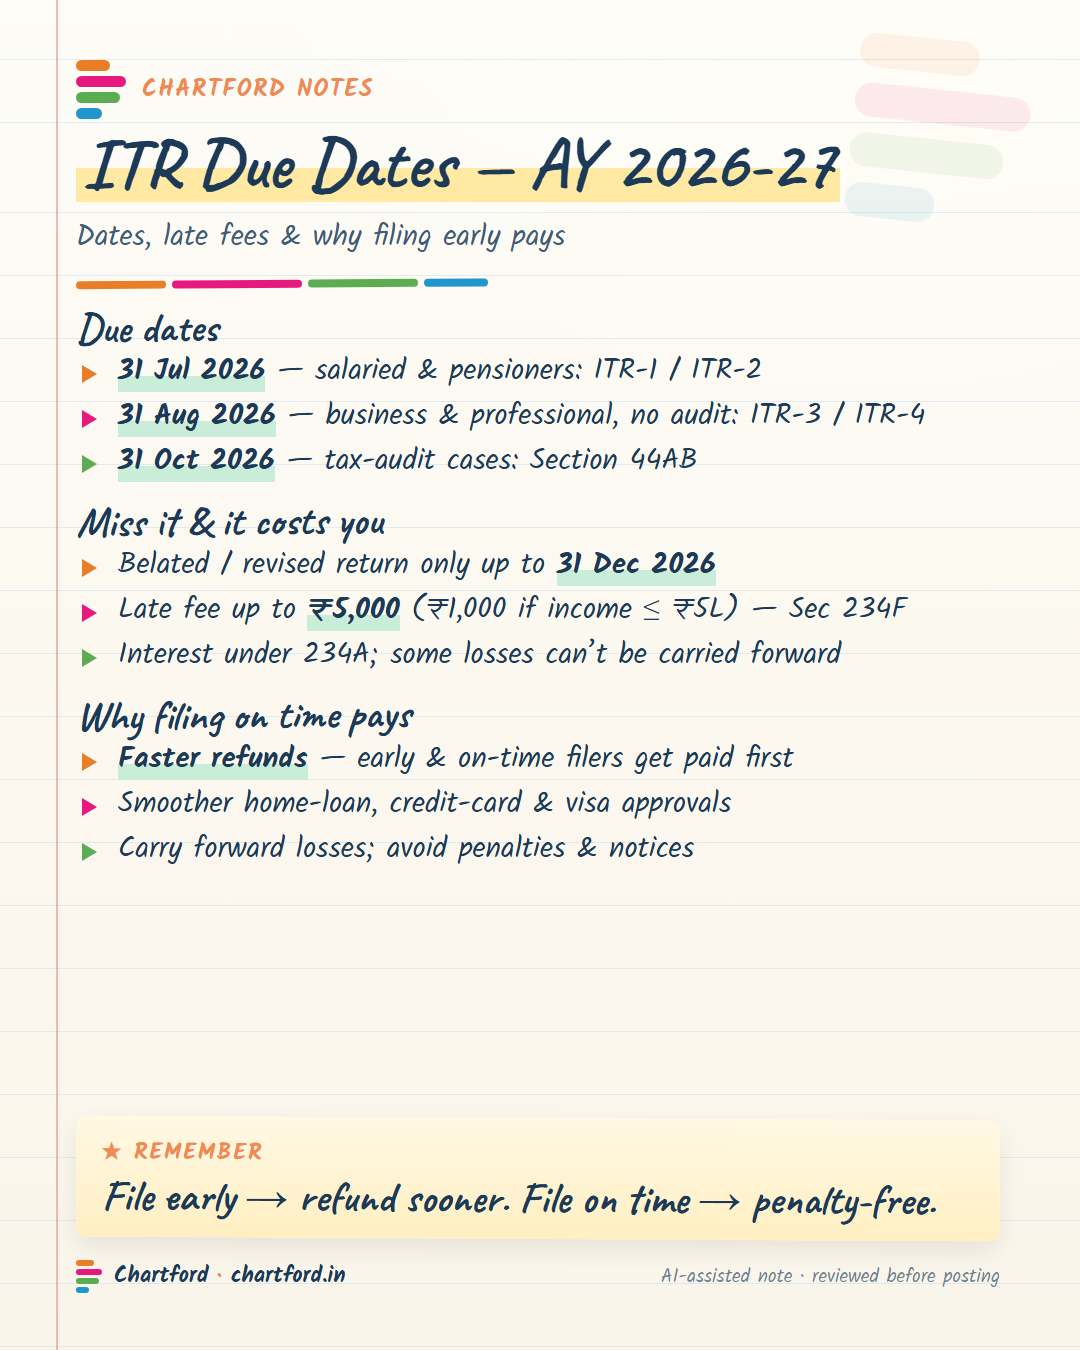 Income Tax
ITR filing due dates for AY 2026-27 — and why filing early pays
ITR due dates for AY 2026-27: 31 Jul salaried, 31 Aug non-audit business, 31 Oct audit. Plus Section 234F late fees and why filing early gets you faster refunds.
Read the note →No articles in this topic yet — we publish here regularly, so check back soon.